Understanding the 2026 Cost-of-Living Adjustment (COLA)
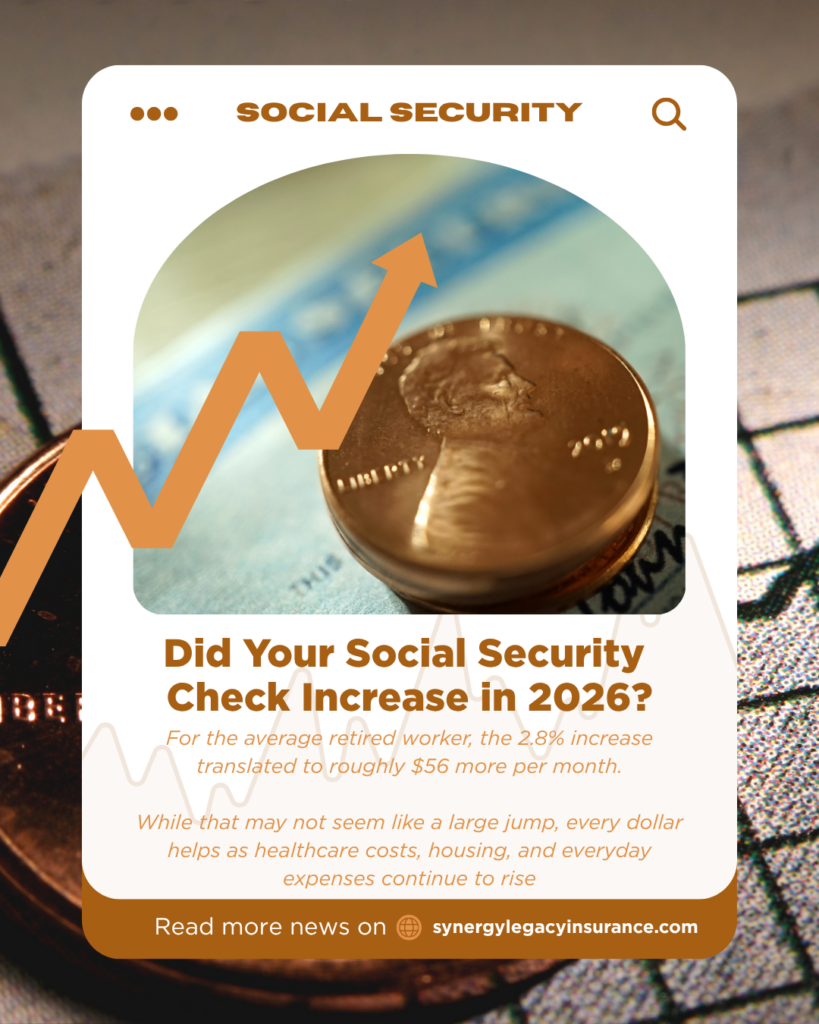
Beginning in January 2026, approximately 72.5 million Americans who receive Social Security or Supplemental Security Income (SSI) received a 2.8% increase in their monthly payments.
This adjustment—known as the Cost-of-Living Adjustment (COLA)—is designed to help offset inflation and preserve the purchasing power of your retirement income.
What This Means for You
For the average retired worker, the 2.8% increase translated to roughly $56 more per month. While that may not seem like a large jump, every dollar helps as healthcare costs, housing, and everyday expenses continue to rise.
Here’s what changed for 2026:
Increased monthly benefit:
The 2.8% increase has been included in eligible 2026 Social Security and SSI payments.
Timing:
Most Social Security recipients began seeing the increase reflected in their January 2026 payments. SSI beneficiaries received their first adjusted payment on December 31, 2025.
How it was calculated:
The adjustment was based on the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W), comparing the third quarter of 2024 with the third quarter of 2025.
Why it matters:
The annual COLA is intended to help Social Security benefits keep pace with inflation and changes in the cost of living.
What You Should Do Next
The 2026 COLA increase is a good reminder to take a closer look at your broader financial and healthcare picture:
Review your Medicare coverage.
Medicare costs and benefits can change annually—especially prescription drug coverage and provider networks. Make sure your current coverage continues to fit your healthcare needs and budget.
Update your financial plan.
Even small increases in income can shift your overall cash flow, potentially affecting taxes, savings strategies, or healthcare spending.
Use direct deposit.
If you haven’t already, consider setting up direct deposit with the Social Security Administration to ensure your payments are received safely and on time.
Planning Ahead
While the 2026 COLA increase offers some relief, it’s important to look beyond annual adjustments.
Building tax-advantaged and predictable income streams—through sound financial planning, annuities, or indexed universal life insurance—can provide additional stability throughout retirement.
Our Commitment to You
Small changes today can have a big impact tomorrow.
Whether you’re reviewing your current Medicare coverage or exploring long-term income protection strategies, we’re here to help you understand your options and make confident, informed decisions.
Schedule your no-cost, no-obligation consultation today: